Portfolio management
Investment Portfolio Management
Independent investment guidance for decisions that deserve a considered plan.
Portfolio management is the ongoing process of building, implementing, monitoring and adjusting a diversified mix of investments so that it keeps working toward your goals. It doesn't end once a portfolio is set up — markets move, life changes, and a portfolio that suited you a few years ago may need adjusting today.
What portfolio management involves
More than picking investments once
Asset allocation
Diversification
Fund or security selection
Risk management
Rebalancing
Fee monitoring
Performance reporting
Tax awareness
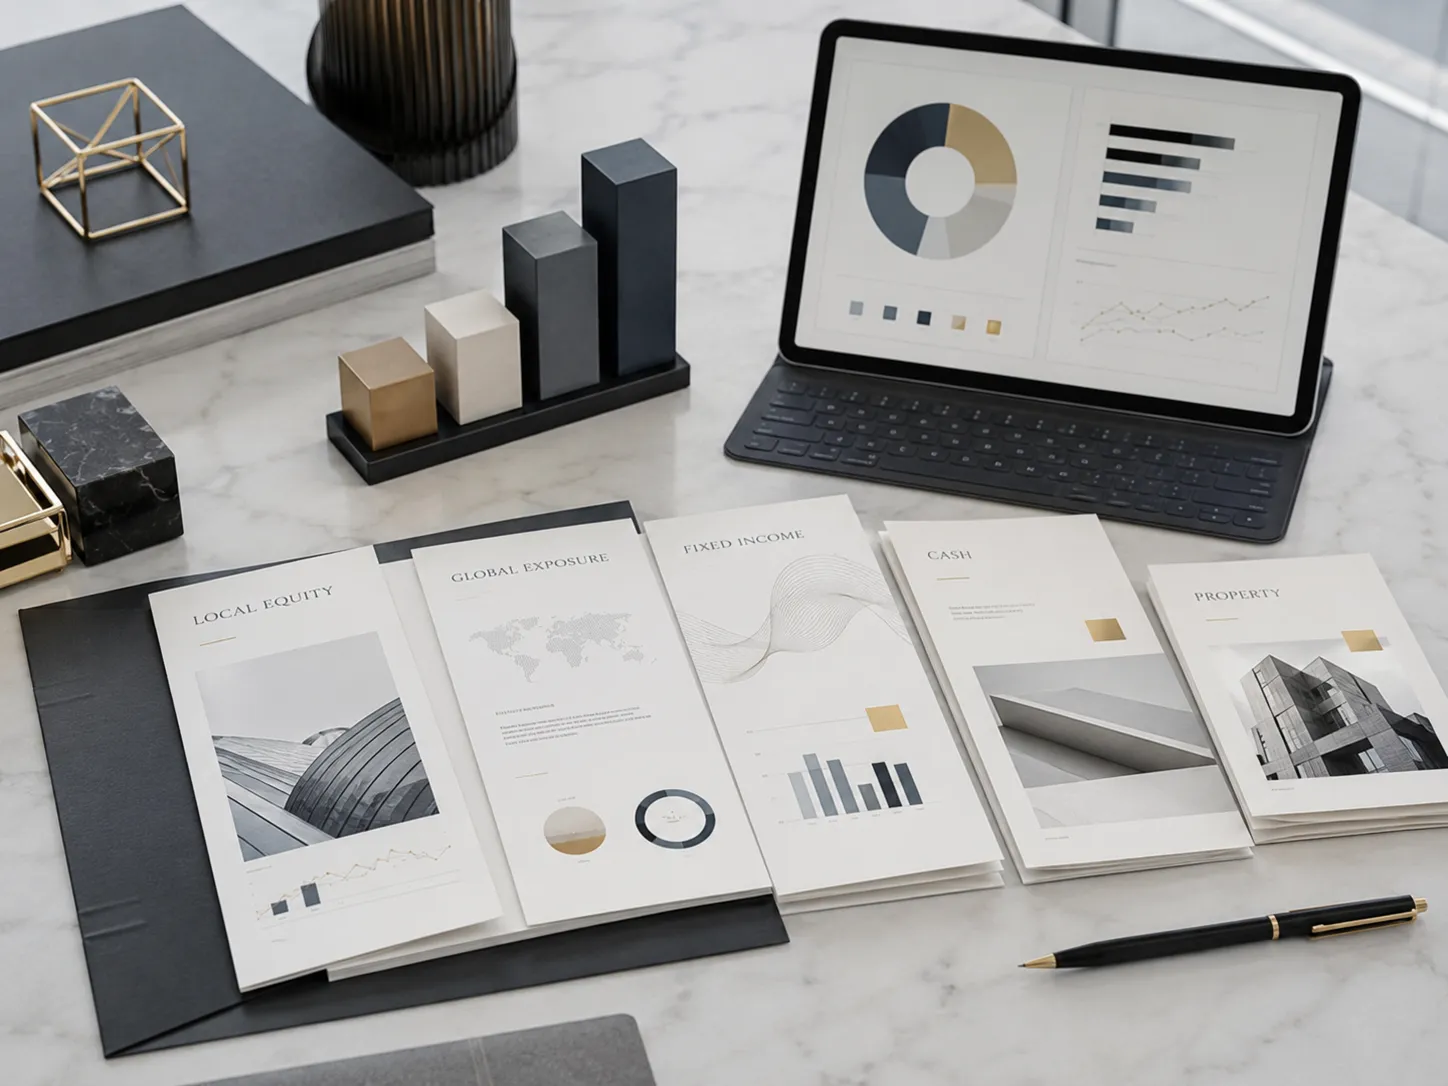
Building a diversified portfolio
The asset classes that make up a portfolio
Cash
Highly liquid and lower-risk, useful for stability and near-term needs.
Bonds
Loans to governments or companies that generally offer more predictable income.
Property
Exposure to real estate, often through listed property funds.
South African equities
Shares in companies listed on the JSE, offering local growth potential.
Global equities
Shares in international companies, adding geographic diversification.
Multi-asset funds
Funds that combine several of these asset classes within one vehicle.
Strategic versus tactical decisions
Long-term structure, with limited adjustment at the edges
Strategic asset allocation is the long-term mix of asset classes set to match your goals, time horizon and risk profile — it forms the backbone of a portfolio and shouldn't shift with every headline. Tactical adjustments are smaller, more limited changes made around that structure in response to specific circumstances or opportunities. This isn't about trying to time markets or predict short-term movements; it's about making measured adjustments within a plan that stays anchored to your long-term strategy.
Portfolio reviews and rebalancing
When a portfolio may need attention
Life changes
Marriage, a new child, a career change or other major life events.
Goal changes
A shift in what you're planning for, or by when.
Risk-capacity changes
A change in your ability or willingness to absorb investment risk.
Significant portfolio drift
When market movements shift the portfolio meaningfully from its target mix.
Retirement transition
Moving from accumulating savings to drawing an income.
Tax or regulatory developments
Changes in legislation that affect suitable structuring.
Reviewing an existing portfolio
What Mbalwa looks for in a portfolio review
Many portfolios are built up gradually, over several jobs, advisers or products, and can end up with issues that aren't obvious from the outside. A review considers duplication across similar funds, concentration in a single asset or sector, excessive or unclear fees, whether each product remains suitable, appropriate offshore exposure, and whether the overall risk level still matches your circumstances.
Understanding performance
Context matters more than a single number
Appropriate benchmark
Performance means little without a fair, comparable reference point.
Relevant time period
Short-term figures can be misleading when viewed on their own.
Risk taken
Higher returns achieved by taking on materially more risk aren't a fair comparison.
Fees
Returns should be considered net of the fees paid to achieve them.
Inflation
Real returns, after inflation, reflect actual growth in purchasing power.
Progress toward goals
Ultimately, performance should be judged against whether you're on track for your own goals.
Reporting and communication
What you can expect to receive
Clients typically receive regular reporting that sets out current holdings, how the portfolio has performed relative to an appropriate benchmark, the fees charged, and any recommended adjustments. Reviews are an opportunity to revisit your goals, ask questions and confirm the plan still reflects your circumstances — not simply to look at a number.
Frequently asked questions
Questions about portfolio management
A portfolio manager, or an adviser overseeing portfolio management, constructs a diversified mix of investments aligned with your goals and risk profile, then monitors, reports on and rebalances that mix as markets and your circumstances change.
There's no fixed schedule — rebalancing is typically considered at least annually, and sooner if a life change, goal change or significant market movement causes the portfolio to drift meaningfully from its intended allocation.
Yes — a portfolio review can assess holdings from other advisers or platforms for duplication, concentration, excessive fees and whether the current mix still suits your goals and risk profile.
A diversified portfolio spreads investments across different asset classes, such as cash, bonds, property, and South African and global equities, so that no single market movement determines the entire outcome.
Fees are deducted regardless of performance, so higher charges compound over time and can meaningfully reduce the capital you end up with, even when the difference looks small year to year. This is why fee transparency and regular review matter as much as fund selection.
Neither approach is universally better — active management aims to outperform a benchmark through fund-manager decisions, while passive investing aims to track a benchmark at typically lower cost. The suitable choice, or blend of both, depends on your goals, costs and preferences.
Diversification and active management aim to manage risk in line with your goals, but they cannot guarantee returns or eliminate the possibility of loss. Please verify current fee and tax figures with your adviser before making decisions.
Related services